In most cases, you cannot sell your current U.S. home and simply carry its mortgage—and its low interest rate—to another house. But that is not because transferring mortgage financing to new collateral is inherently impossible.
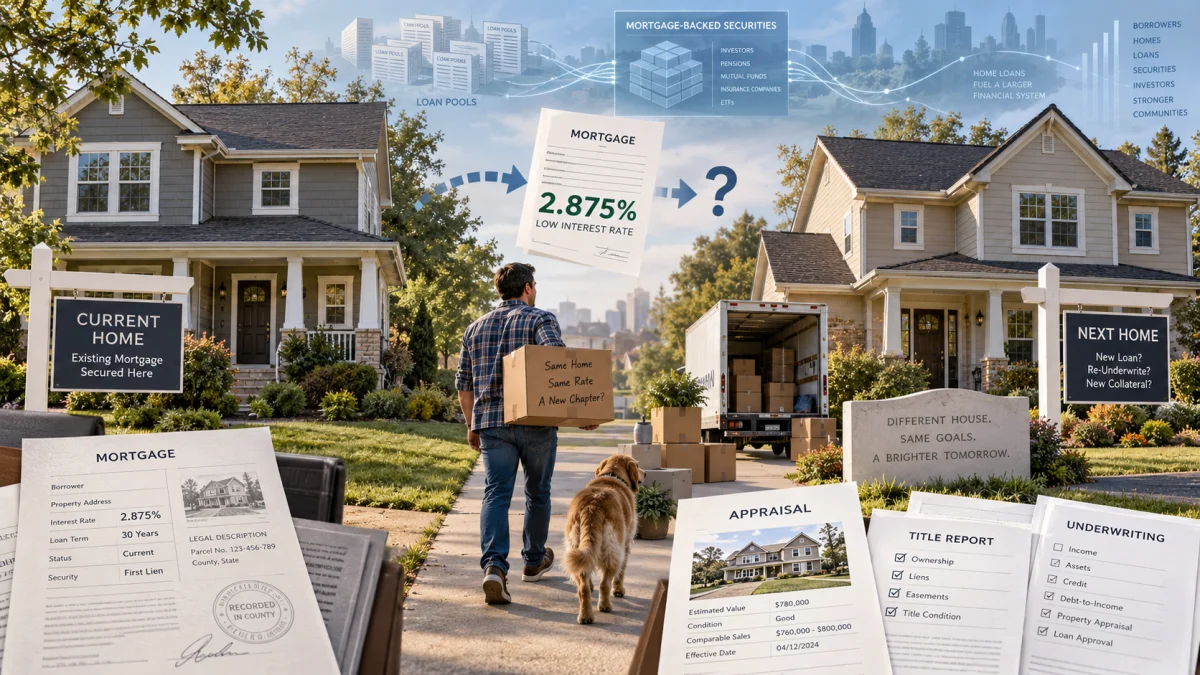
Your mortgage is both a debt you owe and financing secured by a particular property. Standard U.S. conventional mortgages are generally written so that selling that property allows the lender to require the loan to be paid off. The lien on the old house is released, the old mortgage disappears, and financing for the next house is normally a separate transaction at then-current rates.
That system is reinforced by underwriting rules, servicing procedures and the enormous mortgage-backed securities market. A sale of the mortgaged property ordinarily also becomes a prepayment event for whoever owns the mortgage economically.
But none of that proves mortgages cannot be portable.
Fannie Mae already has procedures for substituting mortgage collateral in narrow circumstances. Federal mortgage-tax regulations expressly contemplate replacing one parcel of real-estate collateral with another. Portable mortgages are used in other countries, and E*Trade offered one in the United States more than two decades ago.
The better answer is therefore:
Your mortgage rate normally cannot follow you because mainstream U.S. mortgages were not designed to give borrowers that right—not because moving a mortgage to another property is technically or legally impossible.
That distinction has become unusually important because millions of homeowners still hold mortgages far below prevailing rates.
Your Mortgage Is More Than an Interest Rate
Homeowners understandably think about their mortgage primarily as a personal debt:
I borrowed $350,000. I still owe $350,000. I am still the same borrower. Why should buying a different house change my interest rate?
But a residential mortgage transaction has two closely related pieces.
The promissory note contains your promise to repay the money and establishes terms such as your principal balance, interest rate and repayment schedule.
The mortgage, deed of trust or other security instrument gives the lender rights against a particular property if you fail to meet those obligations.
The Consumer Financial Protection Bureau’s guide to mortgage closing documents makes that distinction explicit: the note establishes the debt, while the security instrument protects the note holder by securing the obligation with the property. (Consumer Financial Protection Bureau)
So a lender has not merely underwritten:
Borrower owes $350,000.
It has underwritten a $350,000 obligation secured by this particular piece of real estate.
Changing the house therefore changes an important part of the transaction even if the borrower remains exactly the same.
Does Federal Law Require Your Mortgage to End When You Sell?
No.
This is one of the most important misconceptions to clear up.
The federal due-on-sale statute, 12 U.S.C. § 1701j-3 defines a due-on-sale clause as a contract provision allowing a lender, at its option, to declare the secured debt due when the property or an interest in it is transferred without the lender’s prior consent. Federal law generally protects lenders’ ability to enforce those provisions, subject to specified exceptions. (U.S. Code)
That is different from a federal law saying:
Every mortgage must legally terminate whenever a house changes hands.
In fact, the statute expressly says it does not prohibit lenders from permitting assumptions.
The more accurate statement is:
Most mainstream U.S. mortgages contain contractual terms under which an ordinary sale of the collateral can trigger repayment of the existing loan.
Fannie Mae’s current Selling Guide for conventional fixed-rate loans says those loans are not assumable as of the note date. Freddie Mac likewise maintains rules governing due-on-sale provisions in its standard mortgage system. (Fannie Mae Selling Guide)
There are statutory exceptions to due-on-sale enforcement—for example, certain transfers involving spouses, children, death or qualifying trusts—but an ordinary sale followed by the purchase of an unrelated replacement home generally is not one of them.
What Actually Happens to Your Mortgage When You Sell?
Imagine you owe $350,000 on House A at 3%.
You sell House A.
At closing, money from the transaction is used to satisfy the existing mortgage. The lien securing that debt is released so the buyer can receive the property without your mortgage remaining attached to it.
If you then purchase House B with financing, a new lien is established against House B under the new financing arrangement.
For most borrowers, that means:
House A mortgage → paid off
House A lien → released
House B → newly underwritten
House B mortgage → new loan at available terms
This process also matters far beyond the closing table because the company collecting your mortgage payment may not actually own your loan.
The CFPB notes that many mortgages are sold after origination and that the servicer receiving your monthly payment may be different from the entity that owns the mortgage. (Consumer Financial Protection Bureau)
That takes us into the secondary mortgage market.
Why Can’t the Lender Just Switch the House?
Because House B is not economically identical to House A.
A replacement property can change the:
- property value and loan-to-value ratio;
- property type;
- title history;
- lien position;
- insurance requirements;
- flood-risk treatment;
- occupancy classification;
- mortgage-insurance requirements;
- eligibility under the mortgage program.
The borrower may be unchanged, but the collateral is not.
That does not mean these issues are impossible to resolve. They are exactly the kinds of issues lenders already evaluate when originating mortgages.
The more interesting evidence is that Fannie Mae already has a formal procedure called “Evaluating a Request for the Substitution of Property Securing a Mortgage Loan”. It requires Fannie approval and addresses matters including zoning, building codes, flood insurance and preservation of Fannie’s mortgage lien. (Servicing Guide)
This is not a normal mortgage-portability program for homeowners selling one house and buying another. The Fannie procedure addresses specialized situations involving matters such as relocating an existing dwelling or demolishing and reconstructing a replacement dwelling.
But it establishes an important point:
The collateral securing an existing mortgage can, under some circumstances, be changed.
So “mortgages simply cannot change collateral” is not an adequate explanation for why ordinary American homeowners cannot port their loans.
Federal Mortgage-Tax Rules Do Not Create an Absolute Barrier Either
Mortgage securitization frequently uses entities known as REMICs—Real Estate Mortgage Investment Conduits—which receive specialized federal tax treatment.
That sounds like another possible hard barrier to changing mortgage collateral.
It is not an absolute one.
Current Treasury regulations at 26 CFR § 1.860G-2 expressly address modifications that release, substitute, add or otherwise alter a substantial amount of real-estate collateral, subject to requirements intended to preserve the mortgage’s qualification as an obligation principally secured by real property. (eCFR)
The regulation even contains an example in which the lien on Property X is released and Property Y is substituted as collateral.
That example arises under particular circumstances and does not grant homeowners a general right to port mortgages. Nor does it prove that every proposed portable-mortgage structure would automatically satisfy REMIC requirements.
It does prove something narrower but important:
Federal mortgage-tax rules themselves contemplate substitution of real-estate collateral.
The barrier to ordinary portability therefore cannot accurately be reduced to “the tax rules forbid changing the house.”
So What Does Securitization Actually Change?
This is where the explanation becomes more economic than legal.
Fannie Mae describes its mortgage-backed securities as beneficial interests in pools of residential mortgage loans held through trusts. Its MBS trust documentation governs the loans, payment flows and servicing obligations associated with those securities. (Fannie Mae)
Fannie’s current Single-Family MBS Prospectus explains what ordinarily happens when property securing a fixed-rate mortgage in one of its pools is sold.
If the relevant due-on-sale clause can be enforced, Fannie says it will enforce it. If it cannot be enforced under applicable law or trust documents, Fannie says it will purchase the mortgage from the pool. In either case, the mortgage’s principal is paid to certificateholders. (Fannie Mae)
That means the sale of your house is normally not just a consumer transaction.
From an MBS investor’s perspective, it is also part of the system determining when mortgage principal comes back.
And that timing has economic value.
Suppose your mortgage pays 3% while new mortgages pay roughly 6.8%.
If you sell under the standard system, the old 3% mortgage is paid off and its principal is returned through the mortgage-finance chain.
If you are instead allowed to carry that 3% debt to another property, the low-rate asset can remain outstanding for longer.
That changes expected:
prepayment speeds, duration and reinvestment timing.
That is the strongest explanation for why securitization matters.
It does not mean securitization makes portable mortgages impossible.
It means a portability right changes the economics of the mortgage and therefore has to be accounted for when the mortgage is designed, priced and securitized.
Why Future Portable Mortgages Are Easier Than Retrofitting Existing 3% Loans
This is an important distinction in the current portability debate.
A lender can originate a new mortgage tomorrow with a contractual provision saying:
Subject to defined underwriting and collateral requirements, this borrower may preserve specified financing terms when purchasing a replacement property.
Everyone buying, servicing, guaranteeing or investing in that mortgage can then price the option from the beginning.
The harder question is what to do with millions of existing mortgages originated without such a contractual right.
Those loans already have:
existing notes and security instruments;
existing servicing agreements;
existing investor expectations;
existing trust and tax structures;
and established rules governing what happens when their properties are sold.
It would be an overstatement to call those arrangements completely immutable. Fannie Mae has repeatedly amended and restated its single-family MBS trust documents, and its current master trust agreement contains formal amendment provisions. (Fannie Mae)
But that does not establish that Fannie, Freddie or a mortgage servicer can simply rewrite an existing borrower’s loan into a portable mortgage without additional legal, contractual, tax and operational work.
The strongest supported conclusion is therefore narrower:
Designing portability into new mortgages is comparatively straightforward. Converting the enormous existing stock of low-rate mortgages would be substantially more complicated—and current evidence does not establish a simple universal mechanism for doing it.
Portable Mortgage vs. Assumable Mortgage: They Solve Different Problems
These terms are frequently confused.
With an assumable mortgage, the house generally stays the same while the borrower changes.
You sell your house, and a qualified buyer takes over the existing mortgage attached to that property.
With a portable mortgage, the borrower stays the same while the house changes.
You sell House A and take some or all of your existing financing to House B.
That distinction matters because FHA and VA assumptions are sometimes cited as proof that Americans can already “transfer” mortgages.
VA describes an assumption as a transaction in which a purchaser takes ownership of the home and assumes liability for the existing mortgage obligation. VA-guaranteed loans can be assumed by qualified buyers under applicable underwriting requirements. VA’s Assumption Entitlement Acknowledgment explains the process directly. (VBA)
FHA mortgages also have assumption procedures.
Those programs can preserve a low rate for the buyer of your current house.
They ordinarily do not let you carry that rate to your next house.
Portable Mortgages Already Work Elsewhere
The United Kingdom provides a useful counterexample to the idea that mortgage portability somehow eliminates underwriting.
The government-backed MoneyHelper service says most UK mortgages are now portable, but moving the mortgage is still treated as a new mortgage application. The borrower must satisfy the lender’s affordability checks and other requirements. (MaPS)
If the homeowner needs more money for a more expensive property, MoneyHelper notes that only the existing balance may retain the old mortgage deal while the additional borrowing receives separate financing terms.
That illustrates an important point.
A “portable mortgage” does not necessarily mean somebody literally edits the address printed on the original loan documents while everything else remains untouched.
A lender can instead discharge the mortgage against House A, secure financing against House B, re-underwrite the transaction and preserve the agreed economic terms for the eligible portion of the debt.
Portability is therefore better understood as financing continuity across a change in collateral.
The United States Has Tried Portable Mortgages Before
Portable mortgages are not purely hypothetical in the United States either.
In June 2003, E*Trade introduced a product marketed as a portable mortgage. Contemporary CNN/Money reporting from the product’s launch described a 30-year fixed-rate mortgage whose rate could be carried to a subsequent home once, subject to eligibility conditions. (CNN Money)
The option was not free.
CNN reported that borrowers paid a premium of three-eighths of a percentage point, or 0.375 percentage point, above the company’s comparable jumbo rate for the portability feature.
Contemporary reporting also noted a central secondary-market problem: E*Trade planned to retain the unusual mortgages in its own portfolio rather than sell them through the ordinary secondary market. (The Washington Times)
That historical experiment is particularly informative because it demonstrates three things at once.
First, U.S. mortgage portability is technically feasible.
Second, the right to preserve a rate when market rates rise has economic value and may therefore cost something upfront.
Third, standardized secondary-market support matters if portability is going to become a mainstream rather than niche product.
Who Ultimately Pays for Mortgage Portability?
There is no free lunch hidden inside a 3% mortgage.
Suppose two otherwise identical borrowers take out 30-year mortgages.
One loan must be repaid when the home is sold.
The other allows its borrower to carry the rate forward through one or more moves.
If rates later rise sharply, the second borrower possesses something valuable: the right to keep financing that is cheaper than the market.
Investors funding that mortgage may therefore expect the low-rate asset to remain outstanding longer than it would under ordinary sale-induced prepayment behavior.
The Urban Institute analyzed this problem in 2025 and estimated that portable mortgages could require an initial mortgage-rate premium of as much as roughly 40 basis points under its assumptions because of longer duration and slower prepayment behavior. Urban’s portable-mortgage analysis is useful here, but that figure is an analytical estimate—not an observed universal price. (Urban Institute)
Interestingly, E*Trade’s historical 0.375-percentage-point premium was in roughly the same range.
That convergence is suggestive, but it should not be treated as proof that a modern nationwide portability option would cost exactly 0.375% or 0.40%.
A standardized Fannie/Freddie market could have very different liquidity, prepayment and pricing characteristics.
What If the New House Costs More?
Suppose you still owe $350,000 at 3%, but your next house requires $550,000 in mortgage financing.
Portability does not necessarily require giving you the entire $550,000 at 3%.
A workable structure could preserve:
$350,000 at the old 3% rate
while financing:
the additional $200,000 at the prevailing market rate.
That is broadly consistent with how porting can work in the UK, and historical reporting on the E*Trade product likewise contemplated additional financing when borrowers needed more money.
The practical challenge would be coordinating those pieces while maintaining the required lien structure and underwriting standards.
There is currently no universal U.S. rule governing such a transaction because there is no standardized mainstream U.S. portable-mortgage program.
What If the New House Costs Less?
That becomes a collateral problem.
Suppose you owe $350,000 but the replacement house is only worth $325,000.
A portability option would not logically require a lender to preserve the entire $350,000 balance regardless of whether the new property adequately secures it.
A future program could require principal reduction, impose a maximum loan-to-value ratio, allow only partial portability, or adopt another mechanism.
What it should not be described as doing—without actual program rules—is automatically moving every dollar of old mortgage debt onto any replacement property the borrower chooses.
That detail becomes especially important when discussing current proposed legislation.
Mortgage Lock-In Is a Real Economic Effect
This issue matters because low-rate mortgages have become unusually valuable.
In its July 2026 Monetary Policy Report, the Federal Reserve said existing-home sales remained at very low levels and identified mortgage “rate lock” as one factor likely holding sales down. The Fed reported that the majority of outstanding mortgages still carried rates below 4%, far below prevailing new-mortgage rates at the time. (Federal Reserve)
Researchers have attempted to quantify the effect.
An FHFA working paper on mortgage lock-in estimated that each percentage point by which market rates exceeded a homeowner’s origination rate reduced the probability of sale by 18.1% in its model and data. The paper estimated 1.33 million foregone sales between the second quarter of 2022 and the fourth quarter of 2023. (FHFA.gov)
Separate Federal Reserve staff research estimated that mortgage-rate lock-in accounted for about 44% of the decline in moves among mortgage borrowers from 2021 to 2022 after the researchers adjusted for selection effects. (Federal Reserve)
Those figures require an important qualification.
Researchers did not observe 1.33 million homeowners individually declaring, “I would have moved but for my mortgage rate.” These are counterfactual estimates produced by economic models.
The defensible conclusion is that mortgage lock-in has a measurable and significant effect on homeowner mobility—not that every missing home sale has one identifiable cause.
What Is a 3% Mortgage Actually Worth?
The difference can be enormous.
As of September 10, 2026, Freddie Mac’s Primary Mortgage Market Survey put the average U.S. 30-year fixed mortgage rate at 6.76%. (Freddie Mac)
Consider a homeowner with:
$350,000 remaining balance
3.00% fixed interest rate
20 years remaining
The remaining principal-and-interest payment is approximately $1,941 per month.
If that homeowner had to replace the same $350,000 balance with another loan amortized over the same remaining 20 years at 6.76%, the payment would rise to approximately $2,663 per month.
That is about:
$722 more every month
$8,667 more per year
$43,336 more in cash payments over the first five years
There is another effect hidden inside those payment numbers.
After five years, the original 3% mortgage would have a remaining balance of roughly $281,081.
The 6.76% replacement loan would still owe roughly $300,786.
Over those five years, approximately $47,546 of the old loan’s payments would have gone to interest, compared with about $110,588 on the replacement loan.
That is roughly $63,042 more interest during the first five years alone.
If both loans remained outstanding for the entire remaining 20 years, the higher-rate loan would require roughly $173,343 more scheduled payments.
That $173,343 figure is not the same thing as saying the old mortgage is “worth $173,343 today.” Future savings occur over time.
Using the 6.76% comparison rate to discount the monthly payment advantage produces a simplified present-value estimate of about $94,900 for the lower-rate financing in this example.
That estimate is useful for understanding magnitude, but it is not a guaranteed market value. Real homeowners sell, refinance, prepay and change financial circumstances, and the calculation excludes taxes, closing costs, points and other transaction differences.
The 30-Year Reset Trap
There is another comparison homeowners should watch closely.
Instead of replacing the old mortgage with another 20-year loan, suppose the borrower takes a new 30-year mortgage for $350,000 at 6.76%.
The payment would be approximately $2,272 per month.
Now the apparent penalty for giving up the old 3% mortgage looks like only about:
$331 per month.
But much of the apparent savings comes from quietly adding ten more years of payments.
A useful “What Is Your Low Mortgage Rate Worth?” calculator should therefore compare both:
the same remaining term, and
the actual new mortgage term being offered.
Otherwise a lower monthly payment can conceal a much longer repayment schedule.
What Does the 2026 MOVE Act Actually Propose?
There is now a federal proposal aimed directly at this issue.
Rep. Thomas Kean Jr. introduced H.R. 10028, the Making Ownership Viable for Everyone Act, or MOVE Act, on August 3, 2026.
As of September 15, 2026, the federal record shows the bill as introduced and referred to the House Committee on Financial Services. It is not law, and it does not currently create a portable-mortgage option for homeowners.
The actual two-page bill text published by GovInfo is unusually concise. If enacted, it would require Fannie Mae and Freddie Mac, within 180 days, to begin purchasing and securitizing qualifying conventional mortgages under which the borrower is permitted by the lender to transfer the mortgage’s interest rate, terms and balance to another property within 90 days after selling the original property. (GovInfo)
The legislation is significant because it directly addresses one of the principal structural obstacles identified in the 2003 E*Trade experiment: mainstream secondary-market support.
But the introduced text leaves major implementation questions unanswered.
It does not specify detailed replacement-property underwriting rules, LTV limits, treatment of mortgage insurance, how additional borrowing would work, treatment of cheaper replacement homes, permissible fees, or the exact mechanism by which a loan would move between properties or securities.
And there is one particularly important question for today’s homeowners.
Would the MOVE Act Let You Port an Existing 3% Mortgage?
The introduced bill does not establish that.
Its language applies to conventional mortgages under which the borrower is permitted by the lender to transfer the rate, terms and balance.
The bill does not contain language automatically rewriting existing mortgage contracts to add that right.
But it also does not expressly say that portability would be available only on mortgages newly originated after enactment.
So two categorical claims circulating around the proposal would both go too far:
“Everyone with an existing 3% mortgage would become eligible.”
The bill does not say that.
And:
“Existing mortgages definitely could never qualify.”
The bill does not expressly say that either.
How legacy mortgages would be handled would require additional implementation decisions, contractual mechanisms, regulations, legislation or some combination of them if the proposal advanced.
Until those rules exist, nobody can responsibly promise an existing homeowner that the bill would let them carry a pandemic-era mortgage into another house.
Would Portable Mortgages Solve the Housing Market’s Supply Problem?
Not by themselves.
Portability could reduce the financial penalty faced by some existing homeowners who want to move. That could increase transactions and allow some homes that are currently “locked in” to come onto the market.
But the seller of one house frequently becomes the buyer of another.
Portability therefore changes mobility and housing-market turnover more directly than it creates net new housing units.
Urban Institute makes this distinction in its analysis, arguing that portability could alleviate mortgage lock-in without solving the underlying shortage of housing supply. (Urban Institute)
That is the more defensible way to frame the potential effect.
Can You Transfer Your Mortgage to Another House Today?
For most U.S. homeowners with standard conventional fixed-rate mortgages, generally not.
Your existing financing normally ends when the house securing it is sold, and the next property requires new financing.
But “generally not” matters.
Mortgage portability is not technically impossible. Specialized lender arrangements can differ. Fannie Mae already permits collateral substitution in narrow circumstances. Assumable government-backed mortgages preserve financing in a different way. And lenders could offer mortgage products specifically designed around portability if the contractual and secondary-market architecture supported them.
If you are considering a move and preserving your current financing would materially affect your decision, the relevant document is ultimately your own mortgage contract, not a generic internet rule.
And if Congress eventually changes the secondary-market framework, the details will matter far more than the word “portable.”
The real question will be:
Which mortgages qualify, how much of the old balance and rate can move, what must the replacement property satisfy, and what does the portability option cost?
Those rules do not yet exist nationally.
But the evidence is already strong enough to answer the larger question.
Your low mortgage rate is not naturally attached to one house forever. The American mortgage system was designed to make the sale of that house ordinarily end the financing. Portability is a different product design—and one the system could adopt if lenders, regulators and the secondary market decide how to price and administer it.
References and Further Reading
Federal law and mortgage documents
12 U.S.C. § 1701j-3 — Preemption of Due-on-Sale Prohibitions — Official U.S. Code text defining due-on-sale clauses, governing their enforceability and listing protected transfers for residential property.
Consumer Financial Protection Bureau — Mortgage Closing Documents Guide — Explains the distinction between the promissory note and the mortgage/security instrument and includes representative due-on-sale language.
26 CFR § 1.860G-2 — REMIC Rules — Treasury regulation addressing qualifying mortgage modifications, including substitution of substantial real-estate collateral under specified conditions.
Fannie Mae, Freddie Mac and securitization
Fannie Mae Selling Guide — Fixed-Rate Loans — Current Fannie eligibility rules stating that conventional fixed-rate loans are not assumable as of the note date.
Fannie Mae Servicing Guide — Release or Substitution of Property Securing a Mortgage Loan — Primary evidence that Fannie has an approval process for collateral substitution in narrowly defined circumstances.
Fannie Mae Single-Family MBS Prospectus, December 1, 2025 — Explains mortgage pools, due-on-sale treatment, assumptions, prepayments and distributions of principal to certificateholders.
Fannie Mae MBS Trust Agreements — Describes the trust structure governing Fannie mortgage-backed securities and links current and historical trust documents.
CFPB — How Can I Tell Who Owns My Mortgage? — Consumer explanation of the distinction between a mortgage owner and the company servicing the loan.
Mortgage lock-in and current rates
Federal Reserve — Monetary Policy Report, July 2026 — Reports that the majority of outstanding mortgages remained below 4% and identifies mortgage-rate lock as a factor restraining existing-home sales.
FHFA Working Paper 24-03 — The Lock-In Effect of Rising Mortgage Rates — Empirical analysis estimating how gaps between existing and market mortgage rates affect sale probabilities and housing-market activity. Its numerical effects are model estimates rather than directly observed counterfactual sales.
Federal Reserve FEDS — Locked In: Mobility, Market Tightness, and House Prices — Separate Federal Reserve staff analysis estimating the contribution of mortgage-rate gaps to reduced homeowner mobility.
Freddie Mac Primary Mortgage Market Survey — Source for the 6.76% average 30-year fixed mortgage benchmark used in the September 2026 worked example.
Portability, assumptions and international comparison
MoneyHelper — Remortgaging and Mortgage Portability — UK government-backed consumer guidance explaining that most UK mortgages are portable but that moving still requires a new application, affordability checks and potentially separate financing for additional borrowing.
Department of Veterans Affairs — Assumption Entitlement Acknowledgment — Primary VA explanation of how a purchaser may assume an existing VA-guaranteed mortgage, illustrating the difference between assumption and portability.
CNN/Money — “Are Portable Mortgages for You?” June 10, 2003 — Contemporary reporting on ETrade’s 2003 U.S. portable-mortgage product, including its pricing premium and qualification rules. Used as historical secondary evidence because an accessible original ETrade product document was not located.
Urban Institute — Portable Mortgages Could Alleviate Homeowner Lock-In but Come with Challenges — Policy analysis of portability, secondary-market liquidity and potential pricing effects. Its rate-premium estimates should be understood as modeled analysis rather than current program pricing.
Proposed 2026 legislation
H.R. 10028 — Making Ownership Viable for Everyone Act, Introduced Text — Official GovInfo text of the proposed MOVE Act. As of September 15, 2026, it remains proposed legislation rather than an available mortgage program.
Editorial currency note: Mortgage rates, Fannie Mae and Freddie Mac servicing rules, federal regulations and the status or text of H.R. 10028 can change. Legislative status and time-sensitive mortgage-market figures in this article were checked through September 15, 2026.