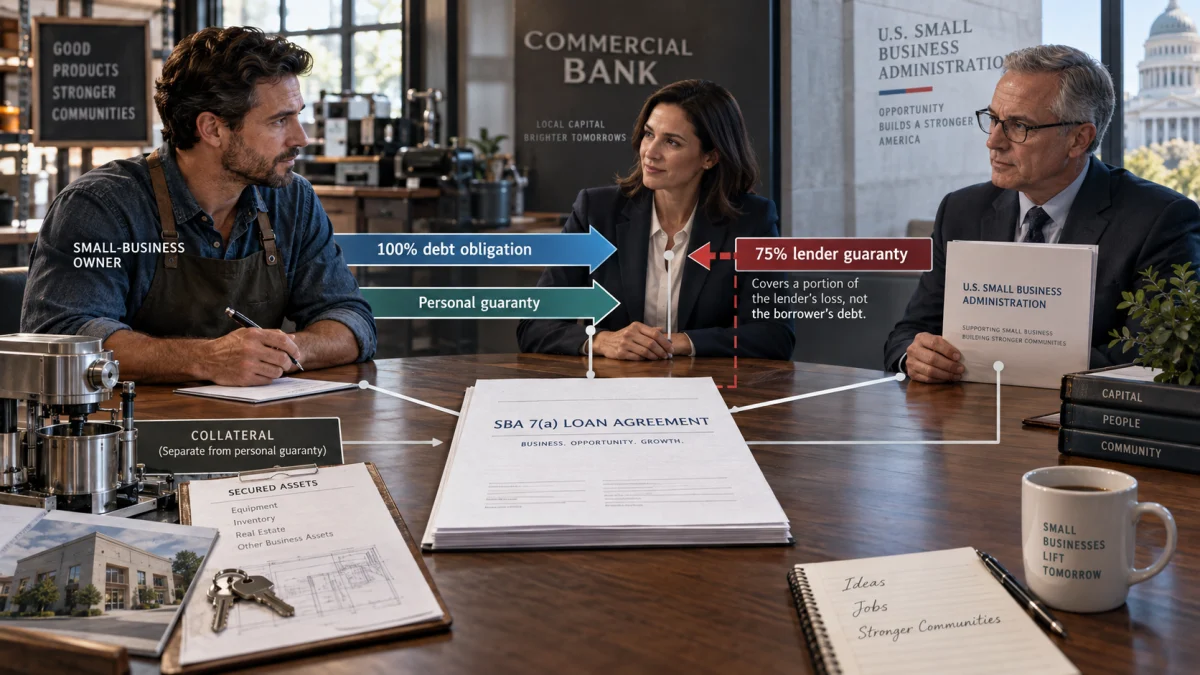
Because the SBA and the business owner are guaranteeing two different things.
The SBA guaranty protects the lender against a defined portion of eligible loan exposure if the borrower defaults and the lender satisfies SBA requirements. The owner’s personal guaranty protects the debt itself by making the owner personally responsible if the business does not pay.
That means a loan described as “75% SBA guaranteed” does not mean the borrower is responsible for only the remaining 25%.
If your business borrows $1 million, the business generally owes $1 million. If you sign an unlimited personal guaranty, that guaranty can support the full obligation rather than merely the lender’s unguaranteed 25% share.
The easiest way to understand an SBA 7(a) loan is to stop thinking of it as one guarantee.
There are really three layers:
Business → owes the loan → Lender
Owner → guarantees the business’s obligation → Lender
SBA → guarantees part of the lender’s eligible exposure → Lender or eligible holder
Once those relationships are separated, the apparent contradiction mostly disappears.
What Does “75% SBA Guaranteed” Actually Mean?
For most SBA 7(a) loans, the federal government does not lend the money directly. A private lender makes the loan, and SBA provides a partial guaranty.
Under the SBA’s current 7(a) program rules, the maximum federal guaranty for most 7(a) loans is:
- 85% for loans of $150,000 or less
- 75% for loans above $150,000
Some specialized programs have different percentages. SBA Express, for example, generally carries a 50% guaranty, while certain export programs can have higher guaranty percentages.
The important word is guaranty.
Federal regulations describe an ordinary SBA-guaranteed 7(a) loan as a deferred participation arrangement. The lender funds and services the loan, while SBA guarantees an authorized portion of it. If the borrower later defaults, SBA may be required to purchase the guaranteed portion, subject to specific conditions.
That structure is described directly in 13 CFR § 120.2.
It does not divide the borrower’s debt into a private part and a government part.
A $1 Million SBA Loan Example
Suppose a business receives a standard $1 million 7(a) loan carrying a 75% SBA guaranty.
| Loan component | Amount |
|---|---|
| Total business loan | $1,000,000 |
| SBA-guaranteed portion | $750,000 |
| Unguaranteed lender portion | $250,000 |
| Amount originally owed by borrower | $1,000,000 |
The mistake is looking at that table and concluding:
“Then I’m only personally responsible for $250,000.”
That is not what the 75% means.
The $750,000 and $250,000 figures describe how credit exposure is divided on the creditor side of the transaction.
They do not change the amount the business borrowed.
The Simplest Way to Think About It
For a $1 million loan:
Borrower obligation: $1,000,000
SBA-guaranteed lender share: up to $750,000
Lender’s unguaranteed share: $250,000
The borrower did not receive a $250,000 loan plus a $750,000 government grant.
It received a $1 million loan.
So Who Does the SBA Guarantee Actually Protect?
The SBA guaranty primarily protects the lender or other eligible holder of the guaranteed portion.
SBA’s own lender materials explain the program in almost exactly those terms: the guaranty allows participating lenders to work with businesses they might not otherwise finance, and following a qualifying default SBA can purchase the guaranteed portion of the loan.
That is one of the central purposes of the 7(a) program.
A lender considering a $1 million small-business loan may be reluctant to bear the entire $1 million credit risk. If SBA guarantees 75% of eligible exposure, the lender can make a loan that might otherwise be too risky under ordinary commercial underwriting.
The federal guaranty therefore makes lending easier.
It does not make borrowing nonrecourse.
Why Does SBA Still Require a Personal Guarantee?
Because reducing the lender’s risk and eliminating the owner’s risk would be two very different policies.
SBA has specifically defended significant-owner personal guarantees as a “prudent and reasonable risk mitigation measure.”
In a 2023 SBA rulemaking on its business-loan programs, commenters asked SBA to remove the personal-guaranty requirement in certain circumstances. SBA rejected that approach, explaining that eliminating required guarantees would shift additional risk onto the broader SBA loan portfolio.
That gives us a better explanation than the phrase commonly used by lenders: “skin in the game.”
The structure is more specific.
The SBA guaranty says, in effect:
If this qualifying loan fails and program requirements have been followed, the government will absorb the guaranteed share of eligible creditor exposure.
The owner’s guaranty says:
If the business does not perform its obligations under the loan, I can also be held responsible under my guaranty.
Those promises address different risks.
The 20% Ownership Rule: What It Actually Means
The percentage that causes perhaps the second-largest misunderstanding is 20%.
Under 13 CFR § 120.160, holders of at least a 20% ownership interest generally must guarantee an SBA business loan.
The SBA Form 148 page states more specifically that individuals owning 20% or more of a small-business applicant must provide an unlimited personal guaranty.
But 20% is an ownership threshold.
It is not a liability percentage.
Owning 20% Does Not Mean You Guarantee Only 20%
Imagine four owners:
- Owner A: 40%
- Owner B: 30%
- Owner C: 20%
- Owner D: 10%
The standard rule generally requires Owners A, B and C to provide the required guaranty because each owns at least 20%.
That does not mean Owner C automatically guarantees only 20% of the debt.
An unlimited guaranty is fundamentally different from a guaranty limited to the owner’s percentage interest.
SBA even maintains a separate Form 148L for limited guarantees, demonstrating that “unlimited” and “limited” guarantees are distinct legal instruments.
The SBA’s instructions for Forms 148 and 148L describe several types of limitations that can apply when a limited guaranty is permitted, including maximum-dollar, percentage, time and collateral-based limitations.
Can Someone Who Owns Less Than 20% Still Have to Guarantee the Loan?
Yes.
The federal regulation expressly allows SBA, or an SBA lender acting under delegated authority, to require guarantees from other individuals or entities when appropriate for credit or other reasons, regardless of their ownership percentage.
So the 20% rule is better understood as:
At 20% ownership, the standard guaranty requirement generally kicks in. Below 20%, a guaranty may still be required.
Personal Guarantee vs. Collateral: They Are Not the Same Thing
This distinction is routinely blurred in explanations of SBA loans.
A personal guaranty answers:
Who has promised to pay?
Collateral answers:
What property secures the obligation?
A lien answers:
What legal interest does the creditor have in particular property?
Those concepts can overlap, but they are not interchangeable.
The SBA’s own guaranty-form instructions make this distinction unusually clear.
If a guaranty is secured by property, SBA instructs lenders to establish that security through the appropriate mortgage, deed of trust or security agreement. The guaranty itself does not magically create a lien on every asset a person owns.
SBA even provides for a limited collateral/recourse guaranty in situations where someone pledges particular collateral but is not personally liable for the entire debt.
That Means “Unlimited Personal Guarantee” Does Not Mean “Automatic Lien on Everything You Own”
An unlimited guaranty means the guaranty itself does not contain a contractual dollar limitation like:
- $100,000 maximum;
- 25% of the debt;
- liability only until principal falls below a certain level.
It does not mean a lender automatically receives ownership or a perfected lien on every house, vehicle, bank account or other asset belonging to the guarantor.
What can actually be reached after default can depend on:
- the note and guaranty;
- mortgages and security agreements;
- lien perfection;
- the type and ownership of the asset;
- state law;
- state and federal exemptions;
- marital or community-property rules;
- bankruptcy law;
- judgments and collection procedures.
That is why “Can an SBA lender take my house?” is a different question from “Did I sign an unlimited guaranty?”
The first requires examining the actual loan documents and applicable law.
Why Require Both Collateral and a Personal Guarantee?
Because they solve different collection problems.
Consider a restaurant borrowing $1 million.
The business might pledge equipment, inventory, receivables or other business property. But if the business fails, used restaurant equipment may sell for dramatically less than its original purchase price.
Collateral therefore might not satisfy the remaining debt.
The personal guaranty provides another potential source of repayment.
At the same time, the SBA guaranty protects the lender against an eligible share of the remaining program loss.
That is why all three can exist simultaneously:
Collateral secures property.
The owner guarantees payment.
SBA guarantees part of the lender’s eligible exposure.
None of those automatically replaces the others.
What Happens When an SBA 7(a) Loan Defaults?
Another widespread misconception is that one missed payment causes SBA to immediately send the bank 75% of the loan.
The actual process is more involved.
Federal regulations and SBA’s National Guaranty Purchase Center guidance contemplate servicing, collection, liquidation and review before or alongside an SBA guaranty purchase.
A simplified sequence looks like this:
Payment problems
↓
Lender servicing or workout efforts
↓
Uncured default and liquidation status
↓
Prudent recovery and collateral efforts
↓
Lender submits guaranty-purchase request
↓
SBA reviews the loan and lender compliance
↓
SBA may purchase, reduce or deny the guaranty claim
↓
Collection and liquidation can continue
For most covered loans, 13 CFR § 120.520 allows a lender to demand that SBA honor its guaranty after an installment has remained in default for more than 60 calendar days, subject to the regulation’s conditions.
Current SBA Commercial Loan Service Center guidance further explains the recovery work lenders are expected to perform.
For loans approved on or after May 14, 2007, current SBA guidance generally requires prudent and commercially reasonable efforts to liquidate business personal-property collateral with an aggregate recoverable value of $10,000 or more before purchase, except in circumstances such as bankruptcy.
The exact procedures vary by loan type and circumstances, but the basic point is simple:
An SBA guaranty is not an automatic check written to the lender the morning after a borrower misses a payment.
SBA Can Reduce or Deny What It Pays the Lender
The federal guaranty is valuable, but it is not unconditional protection against every lending mistake.
When a lender asks SBA to honor a guaranty, SBA reviews whether the lender complied with program requirements, loan terms and prudent lending practices.
The National Guaranty Purchase Center explains that lender deficiencies can result in a repair, meaning a monetary reduction in SBA’s guaranty payment.
In more serious cases, SBA can deny liability under the guaranty.
This is not merely theoretical. An August 2026 SBA Office of Inspector General review examined SBA’s decisions in cases that had been recommended for repair or denial, demonstrating that these reviews are an active part of the guaranty system.
This matters to the borrower because it exposes another flaw in the idea that a “75% guaranteed loan” means the government simply owns 75% of the risk from day one.
The guaranty is governed by conditions.
What Happens After SBA Purchases the Guaranteed Portion?
This is the point at which many explanations of SBA loans become seriously misleading.
SBA paying the lender does not erase the borrower’s debt.
SBA’s National Guaranty Purchase Center gives lenders an unusually direct instruction:
They must pursue the entire indebtedness regardless of the guaranteed percentage or any purchase of the guaranty.
That requirement appears in SBA’s liquidation guidance.
So imagine our $1 million loan has fallen into default.
SBA purchasing its guaranteed interest does not transform the borrower’s remaining obligation into 25% of the original balance.
Instead, the purchase changes the economic relationship among the creditor-side parties.
The underlying borrower and guarantor obligations remain subject to the loan documents, recoveries, settlements, applicable law and subsequent collection activity.
SBA’s Payment Is Not a Second Recovery for the Lender
That does not mean a lender gets paid by SBA and can then keep 100% of everything it later collects.
Post-purchase recoveries are subject to SBA accounting and remittance requirements.
The Commercial Loan Service Center’s post-purchase guidance requires lenders to account for recoveries and remit SBA’s applicable share of net proceeds.
So the structure is not:
SBA pays lender + lender collects everything again = double recovery.
Instead, SBA’s purchase reallocates the creditor-side economic exposure while servicing, liquidation and recovery continue under program rules.
Does SBA Become Your New Lender?
Not necessarily in the simple sense borrowers often imagine.
SBA may purchase the guaranteed portion while the originating lender continues servicing and liquidating the loan. Federal regulations specifically require lenders to continue necessary servicing and liquidation in various post-purchase circumstances.
Under 13 CFR § 120.535, lenders must service and liquidate SBA loans in a commercially reasonable manner consistent with prudent lending standards.
SBA also retains authority to take over servicing, liquidation or litigation itself in appropriate circumstances.
So “SBA paid the bank, therefore I now simply owe SBA” is often too simplistic.
The servicing structure depends on what happened to the loan and guaranteed interest.
Does a Charge-Off Mean the SBA Loan Was Forgiven?
No.
A charge-off is primarily an accounting and servicing action. It should not automatically be read as cancellation of the legal debt.
SBA’s Commercial Loan Service Center explains that after prudent liquidation is completed and a wrap-up report is approved, a remaining balance may be charged off.
The same guidance says eligible remaining obligations can then be referred to the U.S. Department of the Treasury for additional collection, which can include federal collection tools such as administrative wage garnishment.
That would make little sense if “charge-off” meant the borrower had automatically been forgiven.
A useful distinction is:
Charge-off: the creditor treats the balance as uncollectible for accounting or servicing purposes at that stage.
Forgiveness, cancellation or legally effective compromise: the borrower is actually released from some or all of the obligation.
Those are not synonyms.
Can an SBA Borrower Settle the Remaining Debt?
Potentially, but not simply because the business failed.
SBA maintains an Offer in Compromise process for 7(a) and other covered loans.
An Offer in Compromise is a request to resolve liability for less than the full amount owed. SBA requires financial information and supporting documentation and evaluates whether a proposed compromise is appropriate.
It should not be treated as guaranteed debt forgiveness.
The possibility of a compromise exists precisely because there can still be unresolved borrower or guarantor liability after collateral and other recovery efforts have been pursued.
Why the Two Guarantees Are Not Redundant
At this point, the entire system can be reduced to one table:
| Question | SBA guaranty | Personal guaranty |
|---|---|---|
| Who gives it? | U.S. Small Business Administration | Business owner or other guarantor |
| Who is primarily protected? | Lender / eligible holder | Creditor holding the guaranteed debt obligation |
| What risk does it address? | Eligible lender credit exposure | Borrower’s failure to pay |
| Does it reduce what the business borrowed? | No | No |
| Is it automatically paid after one missed payment? | No | Enforcement depends on default and loan documents |
| Can it be limited? | Federal percentage is program-specific | Some guaranties can be limited, but 20%+ individual owners generally provide an unlimited guaranty |
| Is it the same as collateral? | No | No |
The critical sentence is:
The government’s guaranty makes the loan safer for the lender to make. The owner’s guaranty makes the debt harder for a significant owner to walk away from if the business fails.
A Quick SBA Guarantee Calculation
For most 7(a) loans above $150,000:
SBA-guaranteed portion = outstanding eligible principal × 75%
Unguaranteed portion = outstanding eligible principal × 25%
If outstanding principal is $800,000:
75% SBA-guaranteed share: $600,000
25% unguaranteed share: $200,000
But:
Outstanding borrower principal: $800,000
The equation is not:
Borrower owes $200,000
That distinction is the entire reason the phrase “75% SBA guaranteed” creates so much confusion.
Actual SBA purchase amounts can differ because of payments, recoveries, interest rules, guaranty repairs and other program adjustments. The example is intended to show the structure, not predict a particular default settlement.
Frequently Asked Questions
If My SBA Loan Is 75% Guaranteed, Am I Personally Responsible for Only 25%?
No.
The 75% ordinarily describes the SBA-guaranteed share of eligible lender exposure. It does not reduce the business’s underlying debt to 25%.
If you signed an unlimited personal guaranty, the guaranty is not ordinarily limited to the lender’s unguaranteed 25% merely because SBA separately guarantees 75%.
If I Own Exactly 20% of the Business, Do I Have to Personally Guarantee the SBA Loan?
Generally, yes.
Federal regulations say holders of at least a 20% ownership interest generally must guarantee SBA business loans, and SBA’s Form 148 guidance states that individuals owning 20% or more must provide an unlimited personal guaranty.
If I Own Only 10%, Am I Automatically Exempt?
No.
SBA or the lender can require guarantees from owners or other appropriate parties below the 20% threshold when warranted.
Does a Personal Guarantee Automatically Put a Lien on My House?
No.
A personal guaranty and a lien are different legal concepts.
A home can potentially be pledged as collateral through a mortgage or deed of trust, and collection against other assets may become possible after judgment depending on applicable law. But signing an unlimited guaranty does not, by itself, automatically create a perfected lien against every asset you own.
Can a Spouse Be Asked to Sign Without Personally Guaranteeing the Entire Loan?
Potentially.
SBA’s guaranty instructions specifically contemplate circumstances involving collateral, community-property rights and spousal interests in which a spouse may execute documents affecting property without becoming personally liable for the entire debt.
The exact effect depends on the documents and applicable state law.
Does SBA Immediately Pay the Bank When the Business Defaults?
No.
There is a servicing and guaranty-purchase process. For most covered loans, an uncured payment default generally must exceed 60 days before the lender can demand purchase, subject to exceptions and program rules.
SBA also reviews the lender’s compliance before honoring the guaranty.
Can SBA Refuse to Honor Its Guarantee?
Yes.
SBA can reduce a guaranty payment through a repair or, in sufficiently serious circumstances, deny liability when lender actions fail to satisfy program requirements.
If SBA Pays the Bank, Is My Personal Guarantee Gone?
No.
SBA specifically instructs lenders in liquidation to pursue the entire indebtedness regardless of the guaranty percentage or SBA’s purchase of the guaranteed portion.
Can the Lender Collect the Full Debt After SBA Has Already Paid 75% and Keep Both?
Not as a double recovery.
Subsequent recoveries are subject to SBA’s accounting and remittance rules, including allocation of SBA’s applicable share.
Does an SBA Charge-Off Mean the Debt Disappears?
No.
A charged-off balance may still be legally enforceable, and eligible unresolved obligations can be referred for further federal collection.
Can an SBA Personal Guarantee Be Negotiated Away?
The standard SBA requirement is not simply whatever a borrower and lender feel like negotiating.
Individual owners of 20% or more generally must provide the required unlimited guaranty. Limited guaranties exist in the SBA system, particularly for other guarantors and specific structures, but whether one is permitted depends on SBA rules and the transaction.
The Bottom Line
An SBA 7(a) loan can carry both a federal government guaranty and an owner’s unlimited personal guaranty because the two promises do different jobs.
The SBA guaranty protects the lender against an eligible percentage of credit exposure.
The personal guaranty makes the owner responsible for the business’s obligation if the business does not pay.
So when a $1 million SBA loan is described as 75% SBA guaranteed, do not translate that into:
“I am only responsible for $250,000.”
The business still borrowed $1 million.
The 75% figure describes the government’s participation in the lender’s risk, not a 75% reduction in the borrower’s debt.
That distinction is the key to understanding how SBA-backed lending actually works.
This article provides general educational information, not individualized legal or financial advice. The enforceability of a particular guaranty, lien or collection remedy depends on the loan documents, applicable law and the facts of the individual transaction.
References and Further Reading
SBA Program Rules and Guaranty Requirements
SBA Lender Resources and Current 7(a) Guaranty Percentages — U.S. Small Business Administration. Provides current guaranty percentages for major 7(a) loan types and explains how the federal guaranty benefits participating lenders.
SBA Form 148: Unconditional Guarantee — U.S. Small Business Administration. SBA’s official page stating that individuals owning 20% or more of a small-business applicant must provide an unlimited personal guaranty.
Instructions for SBA Forms 148 and 148L — U.S. Small Business Administration. Particularly useful for distinguishing full and limited guarantees, secured and unsecured guarantees, collateral pledges and spousal-interest limitations.
13 CFR § 120.160: Loan Conditions — Electronic Code of Federal Regulations. Establishes the general 20% ownership guaranty rule and SBA’s authority to require guarantees from additional parties.
13 CFR § 120.2: Description of the 7(a) Program — Electronic Code of Federal Regulations. Describes an SBA-guaranteed 7(a) loan as a deferred participation in which SBA guarantees a portion of a lender-made loan.
Default, Liquidation and SBA Guaranty Purchase
13 CFR § 120.520: Purchase of 7(a) Loan Guarantees — Electronic Code of Federal Regulations. Establishes the conditions under which a lender can demand that SBA purchase the guaranteed portion following default.
13 CFR § 120.535: Servicing and Liquidation Standards — Electronic Code of Federal Regulations. Requires lenders to service and liquidate SBA loans using prudent, commercially reasonable lending standards.
SBA National Guaranty Purchase Center — U.S. Small Business Administration. Provides the most useful practical explanation of guaranty purchase, liquidation, litigation, repair and denial. It also explicitly states that lenders must pursue the entire indebtedness regardless of the guaranty percentage or SBA purchase.
SBA Commercial Loan Service Center — U.S. Small Business Administration. Covers default servicing, guaranty-purchase timing, liquidation, Offers in Compromise, charge-off procedures and post-purchase recoveries.
SOP 50 57: 7(a) Loan Servicing and Liquidation — U.S. Small Business Administration. The agency’s detailed operating procedures for servicing and liquidating fully disbursed 7(a) loans.
Why SBA Requires Personal Guarantees
Affiliation and Lending Criteria for the SBA Business Loan Programs — U.S. Small Business Administration, Federal Register. SBA explains in the rulemaking record why it considers the significant-owner personal-guaranty requirement a prudent risk-mitigation measure.
Oversight and Current Policy
SBA’s 7(a) Loan Guaranty Purchase Denial Review Process — SBA Office of Inspector General, August 2026. Recent oversight report examining SBA decisions involving guaranty purchases that had been recommended for repair or denial.
SOP 50 10: Lender and Development Company Loan Programs — U.S. Small Business Administration. SBA’s primary origination-policy document for 7(a) and 504 lending.
Editorial currency note: SBA has published SOP 50 10 8.1 with an effective date of October 1, 2026. This article reflects rules and agency guidance verified in September 2026 and relies primarily on federal regulations, SBA guaranty forms and current servicing guidance for its core conclusions. Borrowers and lenders working on transactions closing after October 1, 2026 should consult the then-current SOP for transaction-specific origination requirements.