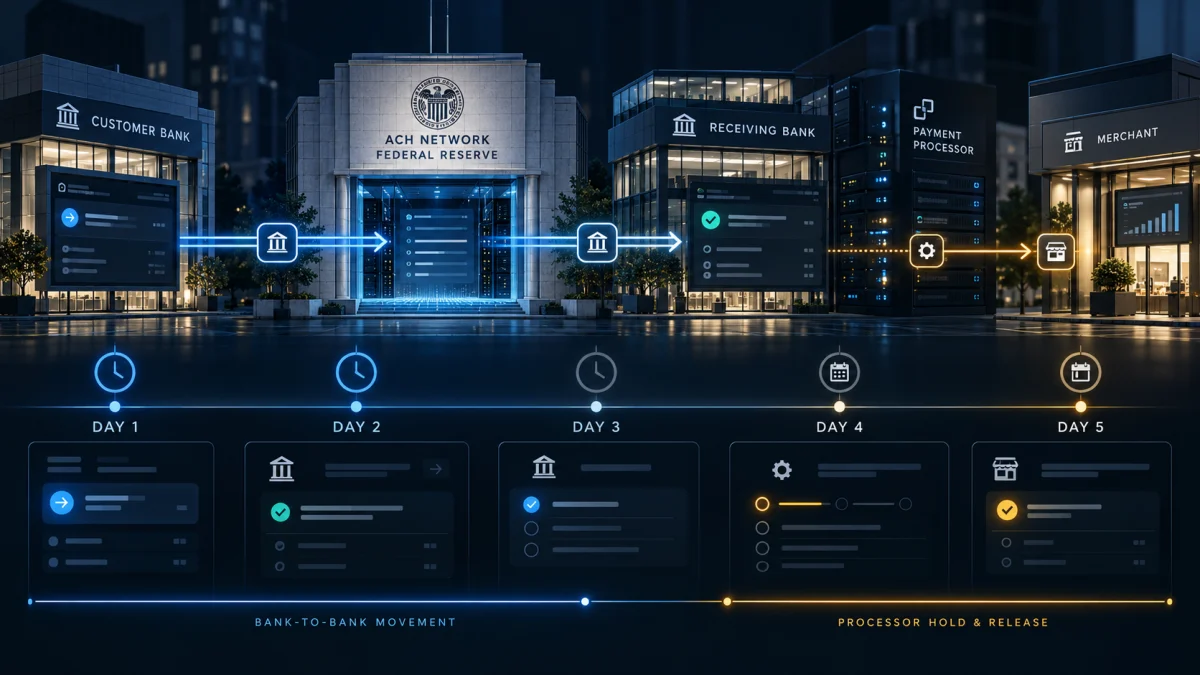
The ACH Network usually is not spending three to five business days moving your money.
According to Nacha’s explanation of ACH settlement, approximately 80% of ACH payments settle within one banking day or less. ACH debits generally settle either the same banking day or the next banking day, while ACH credits can settle the same day, the next banking day or, in some cases, two banking days later.
Yet consumers and businesses routinely encounter messages saying:
“ACH transfer: 3–5 business days.”
Both statements can be true.
The confusion comes from using the phrase “ACH processing time” to describe several different events:
Initiated → Submitted → Settled between banks → Available to the recipient → Confirmed by the processor → Paid out
Those are not interchangeable.
An ACH payment can already be settled between financial institutions while a payment processor is still waiting for the normal debit-return window, applying its own risk controls or preparing a separate payout to the merchant’s bank.
That distinction explains much of the supposed mystery around “slow” ACH payments.
ACH Is Not Just One Overnight Batch Anymore
A common explanation for slow ACH transfers is that banks process ACH payments “in batches.”
That is technically true, but it is increasingly misleading as a complete explanation.
The modern ACH Network operates for approximately 23¼ hours every business day and settles payments four times per day, according to Nacha’s current overview of the ACH Network.
The Federal Reserve’s FedACH processing schedule currently includes Same Day ACH settlement windows at approximately:
- 1:00 p.m. Eastern
- 5:00 p.m. Eastern
- 6:00 p.m. Eastern
Standard or future-dated entries can settle during the following banking day’s morning settlement.
So if somebody initiates an eligible ACH payment early enough on Monday, the ACH Network is not necessarily sitting on that instruction until Wednesday or Thursday.
Depending on the payment type and submission timing, the underlying bank-to-bank settlement may occur Monday or Tuesday.
The more useful question is:
If the ACH Network already settled the payment, what exactly are we waiting for?
The Six Different Clocks Hidden Inside “ACH Processing”
The easiest way to understand ACH timing is to stop treating the entire payment as one clock.
| Stage | What it actually means | Who largely controls it |
|---|---|---|
| Initiated | Someone requested the transfer | Customer, business, bank or processor |
| Submitted | The ACH instruction was actually sent into the network | Bank or processor |
| Settled | Value was exchanged between the financial institutions | ACH operator / Federal Reserve settlement |
| Funds available | The recipient can actually use the credited funds | Bank, subject to applicable ACH rules |
| Payment confirmed | A processor is sufficiently comfortable that the debit will not immediately return | Processor |
| Paid out | Processor sends money from its platform to the merchant’s external bank | Processor and receiving bank |
When an app says “3–5 business days,” it may be describing the entire journey through several of these stages.
That does not mean ACH settlement itself required five days.
“Settled” Does Not Mean the Same Thing Everywhere
This is one of the biggest sources of confusion.
Within the ACH system, settlement generally refers to the transfer of value between the participating financial institutions.
Payment processors sometimes use the word settlement differently.
Stripe, for example, currently lists ordinary ACH Direct Debit as having a four-business-day confirmation and settlement period. But Stripe’s own ACH Direct Debit comparison defines its “settlement time” as the time required for funds to become available in the merchant’s Stripe account.
That is a product-level milestone.
It should not be confused with the earlier Federal Reserve/Nacha settlement event between financial institutions.
So when you see:
“ACH settled Tuesday.”
and:
“Funds available Thursday.”
those statements may describe two completely different stages of the same payment.
Neither is necessarily wrong.
ACH Credits and ACH Debits Behave Differently
This distinction becomes even more important when comparing ACH credits with ACH debits.
An ACH credit is essentially a push.
Examples include:
- payroll direct deposit;
- a company sending a refund;
- certain bank-to-bank transfers;
- government benefits;
- a business sending payment to another party.
An ACH debit is a pull.
Examples include:
- a merchant pulling money from a customer’s checking account;
- recurring utility payments;
- subscription payments;
- ACH Direct Debit through a payment processor.
Those two payment directions create very different risk profiles.
ACH credit
With a credit, the sending side pushes the payment toward the recipient.
Once the payment reaches its settlement date, ACH rules increasingly require rapid availability to the receiving customer.
ACH debit
With a debit, the receiving merchant or processor has effectively requested money from somebody else’s account.
The debit can settle quickly.
But that does not mean the possibility of a subsequent return has disappeared.
That difference is a major reason direct deposit can feel almost instantaneous while paying a business by ACH can still produce a multi-day waiting period.
A Major ACH Rule Changed on September 18, 2026
The gap between settlement and funds availability has also recently narrowed for ACH credits.
Effective September 18, 2026, Nacha changed its rules for non-Same Day ACH credits.
Under the new funds-availability requirement, receiving financial institutions generally must make a non-Same Day ACH credit available for withdrawal no later than 9:00 a.m. local time on its settlement date.
The rule eliminated an older condition tied to whether the receiving institution had received the ACH file by 5:00 p.m. the previous day.
That matters because some older ACH explainers still make it sound as though money can routinely settle at the receiving bank and then simply sit there for another day or two before a normal ACH credit becomes available.
That description is increasingly outdated.
The September 2026 change applies specifically to ACH credits. It does not eliminate the separate risk issues associated with merchants accepting ACH debits.
So Why Can an ACH Debit Still Take Several Days?
Because settling the debit and trusting the debit are different problems.
Imagine a business pulls $5,000 from a customer’s checking account on Monday.
Depending on the submission method and timing, the ACH debit may settle Monday or Tuesday.
At that point, the ACH Network may have completed the bank-to-bank settlement.
But the processor accepting the payment still has another question:
Could this debit come back?
The answer can be yes.
ACH rules permit financial institutions to send return entries after the original payment has settled.
That is not evidence that the original settlement never occurred. A later return is another transaction that reverses the economic result of the original payment.
This is why describing ACH settlement as “not really final” can itself be misleading.
A better way to put it is:
Settlement is a real event, but settlement does not eliminate every possibility of a later ACH return.
The Return Window Is the Missing Piece in Many Explanations
For many ordinary ACH problems, financial institutions have relatively short return windows.
But unauthorized debits can receive different treatment.
Under Nacha’s rules regarding unauthorized debit returns, an unauthorized debit to a non-consumer account generally must be returned so that it reaches the originating institution by the opening of business on the second banking day following settlement.
For qualifying unauthorized debits to consumer accounts, the ACH return timeframe can extend to the banking day following the 60th calendar day after settlement, subject to the applicable requirements.
That does not mean payment processors hold every consumer ACH payment for 60 days.
They do not.
It means there is no universal moment immediately after ACH settlement when every conceivable return risk disappears.
Processors instead decide how much risk they are willing to take and when they are willing to release the money.
Stripe Shows Why Same Day ACH Does Not Mean Same-Day Confirmation
Stripe provides a particularly useful real-world example.
Its standard ACH Direct Debit product currently advertises approximately four business days for payment confirmation and funds availability within Stripe.
Stripe also offers faster processing that uses Same Day ACH rails.
You might reasonably expect that to make the entire payment same-day.
It does not.
In Stripe’s explanation of its faster ACH settlement option, the company explicitly notes that using Same Day ACH does not mean the payment becomes immediately available and confirmed.
Why?
Because the customer’s bank can still return the debit after the underlying ACH movement has occurred.
Stripe therefore separates:
how quickly ACH moves the payment
from:
how quickly Stripe is willing to treat the payment as confirmed and usable.
That distinction is basically the answer to the entire 3–5-day ACH puzzle.
A Monday $5,000 ACH Payment Can Have Several Different Timelines
Consider four transfers involving the same hypothetical $5,000.
Scenario 1: Payroll direct deposit
An employer submits payroll in advance with Friday as the settlement date.
The ACH credit settles Friday morning.
Under applicable funds-availability rules, the employee’s bank generally makes the money available by the required time on the settlement date.
Some banks go even further and offer early direct deposit, effectively advancing the funds before ACH settlement occurs.
The employee may therefore experience ACH as nearly instant.
Scenario 2: Bank-to-bank ACH credit
A customer tells Bank A to send $5,000 to Bank B.
If Bank A actually submits the ACH credit Monday and the payment settles Tuesday, the ACH-network portion of the transfer may be substantially complete by Tuesday morning.
If the customer’s app originally said “2–3 business days,” that longer estimate may include Bank A’s submission procedures, fraud controls, Bank B’s posting process or other product-specific timing.
The phrase “ACH takes three days” tells you very little by itself.
Scenario 3: Merchant ACH debit
A merchant pulls $5,000 from a customer’s account Monday.
The debit settles Tuesday.
The merchant or processor may nevertheless wait longer before treating the money as freely usable because certain returns can arrive after settlement.
The network has finished one stage.
The processor has not finished managing the payment.
Scenario 4: ACH payment followed by merchant payout
Now add a payment platform.
The customer’s ACH debit settles.
The processor waits through its designated confirmation or risk period.
The processor moves the funds into the merchant’s available platform balance.
The merchant then requests or automatically receives a separate payout to its bank account.
That payout has its own processing timeline.
A merchant who started the process Monday might therefore not see spendable money in its external bank until several business days later even though the original ACH debit settled much earlier.
This is how a genuinely fast payment rail can produce a genuinely slow end-user experience.
Where Do the Extra Days Actually Come From?
If an ACH transaction takes three to five business days end to end, the additional time usually comes from some combination of the following.
1. The payment was not submitted immediately
Clicking “transfer” does not guarantee that the financial institution immediately sent the entry into the ACH Network.
A company may collect payment instructions and submit them according to its own schedule or cutoff.
That delay happens before ACH settlement even begins.
2. The transaction missed a processing cutoff
ACH has multiple processing windows, but those windows still have deadlines.
A request made after a provider’s cutoff may not enter the relevant processing cycle until the next banking day.
The important distinction is between the ACH Network’s cutoff and the earlier cutoff your bank or processor chooses for its customers.
A service can impose an earlier deadline than the underlying ACH operator.
3. A weekend or federal holiday intervened
ACH processing has dramatically expanded, but traditional ACH settlement still operates on banking days.
Nacha notes that Federal Reserve settlement is generally unavailable on weekends and federal holidays.
A transfer initiated Friday evening can therefore produce a very different calendar experience from an identical transaction initiated Tuesday morning.
4. The receiving bank has not reached the applicable availability deadline
For ACH credits, availability rules matter separately from settlement rules.
The September 18, 2026 change now generally requires non-Same Day ACH credits to be available by 9:00 a.m. local time on the settlement date.
That reduces one potential source of delay, but it does not make every ACH product instantaneous.
5. A processor is waiting for potential returns
This is especially important with ACH debits.
The processor may receive the interbank settlement and still choose not to release the money immediately.
That waiting period is a risk-management policy, not evidence that the ACH Network is still carrying the payment across the banking system.
6. The merchant still needs a payout
For processor-mediated payments, money becoming available inside a Stripe or similar platform is not necessarily the final destination.
Sending that money to the merchant’s external bank can be a separate transfer.
Again:
payment settlement ≠ processor balance availability ≠ external-bank payout
Why Does Direct Deposit Feel Faster Than Paying by ACH?
Because direct deposit and merchant ACH payments solve different problems.
Payroll is normally an ACH credit.
The employer knows exactly how much it intends to send, payroll files can be submitted before payday, and the payment has a predetermined settlement date.
There is no merchant wondering whether it successfully pulled money from an unwilling or underfunded customer.
A merchant ACH debit runs the opposite direction.
The merchant is requesting money from the customer’s account.
That introduces return risk, including situations involving insufficient funds, closed accounts, incorrect information and unauthorized transactions.
So when someone says:
“My paycheck arrives instantly. Why does an ACH payment take four days?”
the answer is not that one transaction uses modern ACH while the other uses some ancient version.
They can use the same underlying network.
Their direction, risk and product lifecycle are different.
Does Same Day ACH Solve the Problem?
It solves one part of the problem.
Same Day ACH accelerates network processing and settlement.
That can be extremely valuable.
But it cannot by itself eliminate:
- fraud screening;
- authorization problems;
- ACH returns;
- processor risk policies;
- merchant payout schedules;
- weekends affecting later transfers;
- a recipient institution’s separate internal processes.
Stripe’s faster ACH product demonstrates this directly: even when Same Day ACH rails are used, the company does not necessarily treat the transaction as immediately confirmed.
So “Same Day ACH” means what the name says:
the ACH entry can settle through the network that day.
It does not mean every company involved must instantly release the money with zero remaining risk.
Can an ACH Payment Fail After It Says “Settled”?
Yes, depending on what “settled” means and what happens afterward.
This is another case where terminology matters.
If interbank ACH settlement has occurred, the settlement happened.
But a receiving institution may subsequently send a valid return entry.
That return creates another movement of money.
Similarly, a payment processor may show a transaction as having progressed through one stage while still retaining the ability to remove funds if a subsequent return arrives.
The useful question is therefore not simply:
Has the ACH settled?
It is:
Settled where, and what risks or processing steps still remain?
Is the Bank Just Holding My Money?
Sometimes a financial institution or processor really is adding a delay.
But that does not automatically mean anything improper is happening.
The delay might be caused by:
- a product-specific submission schedule;
- a cutoff;
- fraud review;
- account verification;
- ACH debit return risk;
- a processor’s reserve or risk policy;
- a separate payout schedule.
For ACH credits, current Nacha availability requirements place meaningful limits on how long a receiving institution can wait after the settlement date before making the credit available.
For processor-mediated ACH debits, however, a company may legitimately have its own risk period after network settlement.
So the statement:
“Banks secretly hold ACH money for five days even though it already arrived.”
is too broad to be reliable.
In some transactions, the network itself genuinely has not settled yet.
In others, the network has settled but another institution has not released the funds.
The entire point is determining which stage is actually causing the delay.
ACH Timeline Decoder: How to Figure Out Where Your Payment Is Waiting
When an ACH transfer appears stuck, ask these questions in order.
1. Is this an ACH credit or an ACH debit?
If money is being pushed to you, it is generally a credit.
If a company is pulling money from an account, it is generally a debit.
That distinction changes both the timing and the return-risk analysis.
2. When was the transfer actually submitted?
Do not assume the moment you clicked the button was the moment the ACH entry entered the network.
Look for language such as:
- initiated;
- pending;
- submitted;
- processing;
- sent to bank.
3. Has interbank settlement occurred?
If yes, the ACH Network may already have completed its main role.
The remaining delay may be somewhere else.
4. Is the issue funds availability?
For an ACH credit, check whether the receiving bank has posted and released the funds.
For non-Same Day credits, the September 2026 rule generally requires availability by 9:00 a.m. local time on the settlement date.
5. Is a processor sitting between the banks?
If Stripe or another payment processor is involved, distinguish ACH-network settlement from the processor’s confirmation or funds-availability date.
Those are different milestones.
6. Is there another payout after that?
If the money is sitting in a merchant platform balance, the ACH payment may effectively be complete while a completely separate payout still remains.
Once you separate these events, “3–5 business days” stops being a very useful description of ACH itself.
It is better understood as an estimate for the whole financial product wrapped around ACH.
The Bottom Line
ACH usually is not taking three to five business days simply to move money between banks.
Nacha estimates that roughly 80% of ACH payments settle within one banking day or less, and the modern network processes payments throughout most of every banking day with multiple settlement windows.
The longer timeline many consumers and merchants see can include something much broader:
requesting the transfer, submitting it to ACH, interbank settlement, making funds available, waiting for possible debit returns, processor confirmation and finally paying the merchant’s bank.
That distinction matters because all of those stages are routinely described with the same vague words:
pending, processing, clearing, settled, complete.
They are not the same thing.
Sometimes ACH genuinely has not settled yet.
Sometimes ACH finished yesterday and the processor is still managing return risk.
And sometimes the original payment is complete while a second payout has not even started.
So when a bank, fintech app or payment processor tells you an ACH transfer takes 3–5 business days, the most useful follow-up question is not:
Why is ACH so slow?
It is:
Which part of those 3–5 days is actually ACH?
References and Further Reading
ACH Network Rules and Settlement
How ACH Payments Work — Nacha
Nacha’s current explanation of ACH credits, ACH debits and settlement timing, including its estimate that approximately 80% of ACH payments settle within one banking day or less.
The ABCs of ACH — Nacha
Explains modern ACH operating hours, the network’s multiple daily settlement cycles and common practices involving direct deposit and banking days.
FedACH Processing Schedule — Federal Reserve Financial Services
The Federal Reserve’s processing and settlement timetable, including current Same Day ACH transmission deadlines and settlement windows.
Funds Availability and Returns
Funds Availability Requirements for Non-Same Day Credit Entries — Nacha
The rule effective September 18, 2026 requiring non-Same Day ACH credits generally to be available by 9:00 a.m. local time on the settlement date.
Limitation on Warranty Claims and Unauthorized Debit Return Timing — Nacha
Useful for distinguishing ordinary settlement from the later return procedures applicable to unauthorized consumer and non-consumer ACH debits.
Processor Timing
US Bank Debits and ACH Direct Debit — Stripe
Shows Stripe’s current confirmation and funds-availability timelines and, importantly, defines the company’s quoted “settlement time” in terms of funds becoming available inside the Stripe account.
Two-Day Settlement for ACH Direct Debit — Stripe Support
Explains why using Same Day ACH rails does not necessarily mean same-day payment confirmation, including the continuing possibility of returns after network settlement.
Editorial currency note: ACH processing schedules, Nacha rules, Same Day ACH limits and individual bank or processor policies can change. This article reflects rules and documentation reviewed through September 2026. Provider-specific estimates should always be checked against the institution currently handling the transaction.